Quick gut reaction. Which investment do Americans trust more than stocks, gold, savings accounts, and bonds? The answer hasn't changed in 14 years. It's real estate. And this year, that answer
Dated: June 2 2026
Views: 49
Let's be real with each other for a second about affordability. Because you deserve someone who will be honest and transparent about what’s going on, especially if you’ve got a move on your mind.
Here’s the full picture of what’s happening and why. The good – and the bad. So, you know what it truly means for your move. Because while rates are certainly a big part of affordability, they’re not the only factor at play.
After a year or more of rates trending down, they’ve started to climb again. And, if you’re looking to buy, that’s not what you want to see. But it has happened. And here’s why.
Uncertainty is the enemy of mortgage rates.
And with lingering global uncertainty, ongoing tensions in the Middle East, and inflation refusing to fully cool off, there’s a lot that’s having an effect on rates. Colin Robertson, Founder of The Truth About Mortgage, put it plainly:
"You can't have $100 a barrel oil and not expect inflation to rise, which translates to higher bond yields and mortgage rates."
Take a look at the graph below. It uses data from Mortgage News Daily to show just how much all of those factors have had an impact:
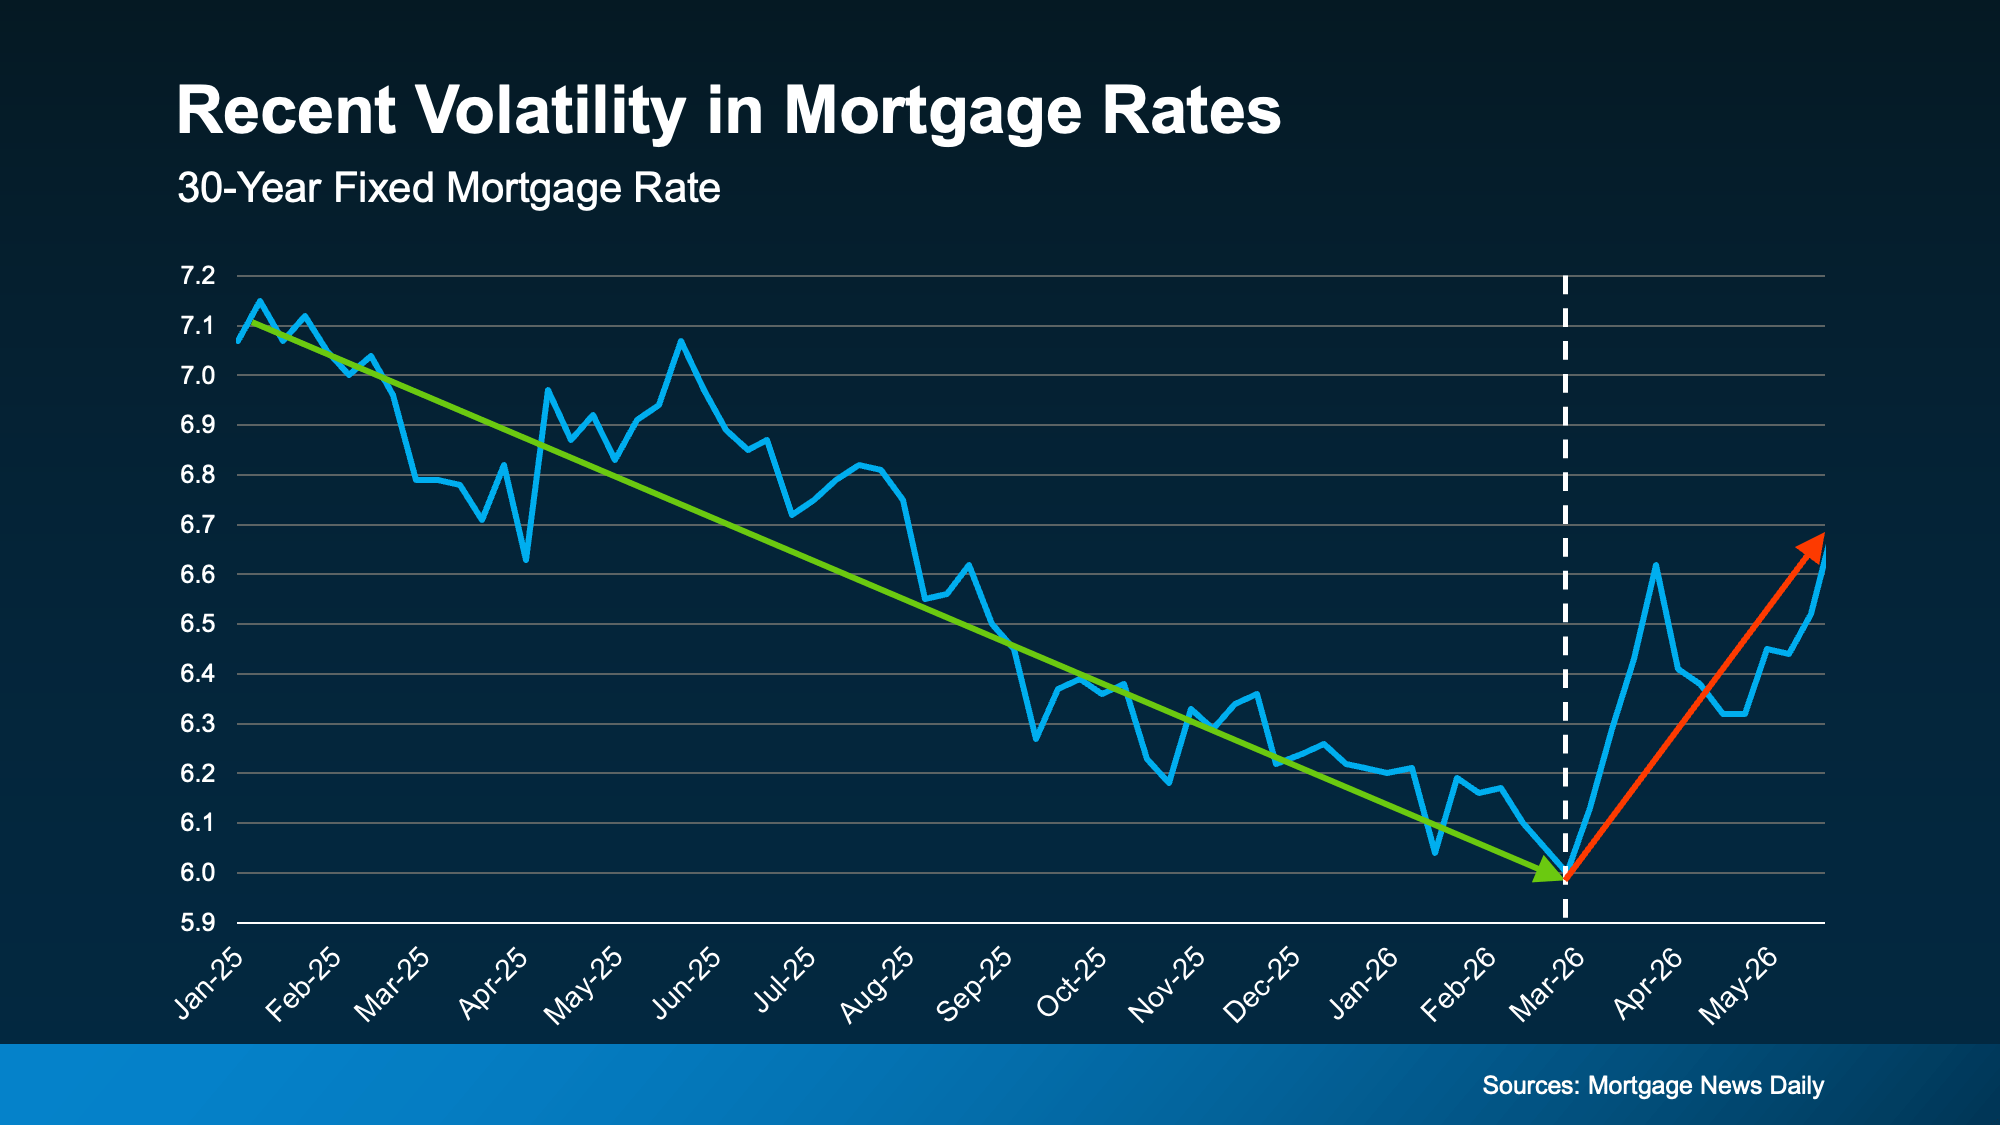 It’s a pretty sharp contrast from where we’ve been, in a relatively short window. And it's probably making you wonder: Should I just wait this out? Will rates fall when the uncertainty eases?
It's possible. But it all depends on how the ongoing geopolitical conflict plays out and whether inflation continues to run hot afterwards – and for how long.
Rates probably aren't heading down until both of those things improve. And even when that does happen, experts agree rates likely won’t be dramatically lower – maybe in the low to mid-6s. That's the reality, and it's worth knowing.
So, should you wait for lower rates? The general consensus is, if you can afford to buy and you find a home you like, it’s still worth it. Because no one knows for sure when rates will start to come back down – and how long do you really want to put your life on hold?
You've probably heard that inflation is making everything more expensive, and there's no shortage of headlines about the cost-of-living outpacing paychecks. It's a legitimate concern. And maybe you’re feeling the pinch yourself. But here's what doesn't make the headlines. It's not all bad news.
Data from the Federal Reserve Bank of Atlanta and Redfin shows wages have actually been growing faster than home prices.
Recently, wages have been increasing at around 4% year-over-year.
And home price growth is closer to 2% year-over-year.
As a buyer, you want your income to rise faster than prices because that helps make your purchase more manageable financially, and it quietly chips away at the affordability challenge over time. That’s exactly what we’re seeing lately. And every little bit is going to help.
A big reason wages have been gaining ground on home prices? Home prices have actually stayed pretty steady.
Check out the graph below. It shows home price data from the National Association of Realtors (NAR) over the past 4 years. Notice anything? There's been no dramatic runup, and no crash either. Just relative stability and slow growth:
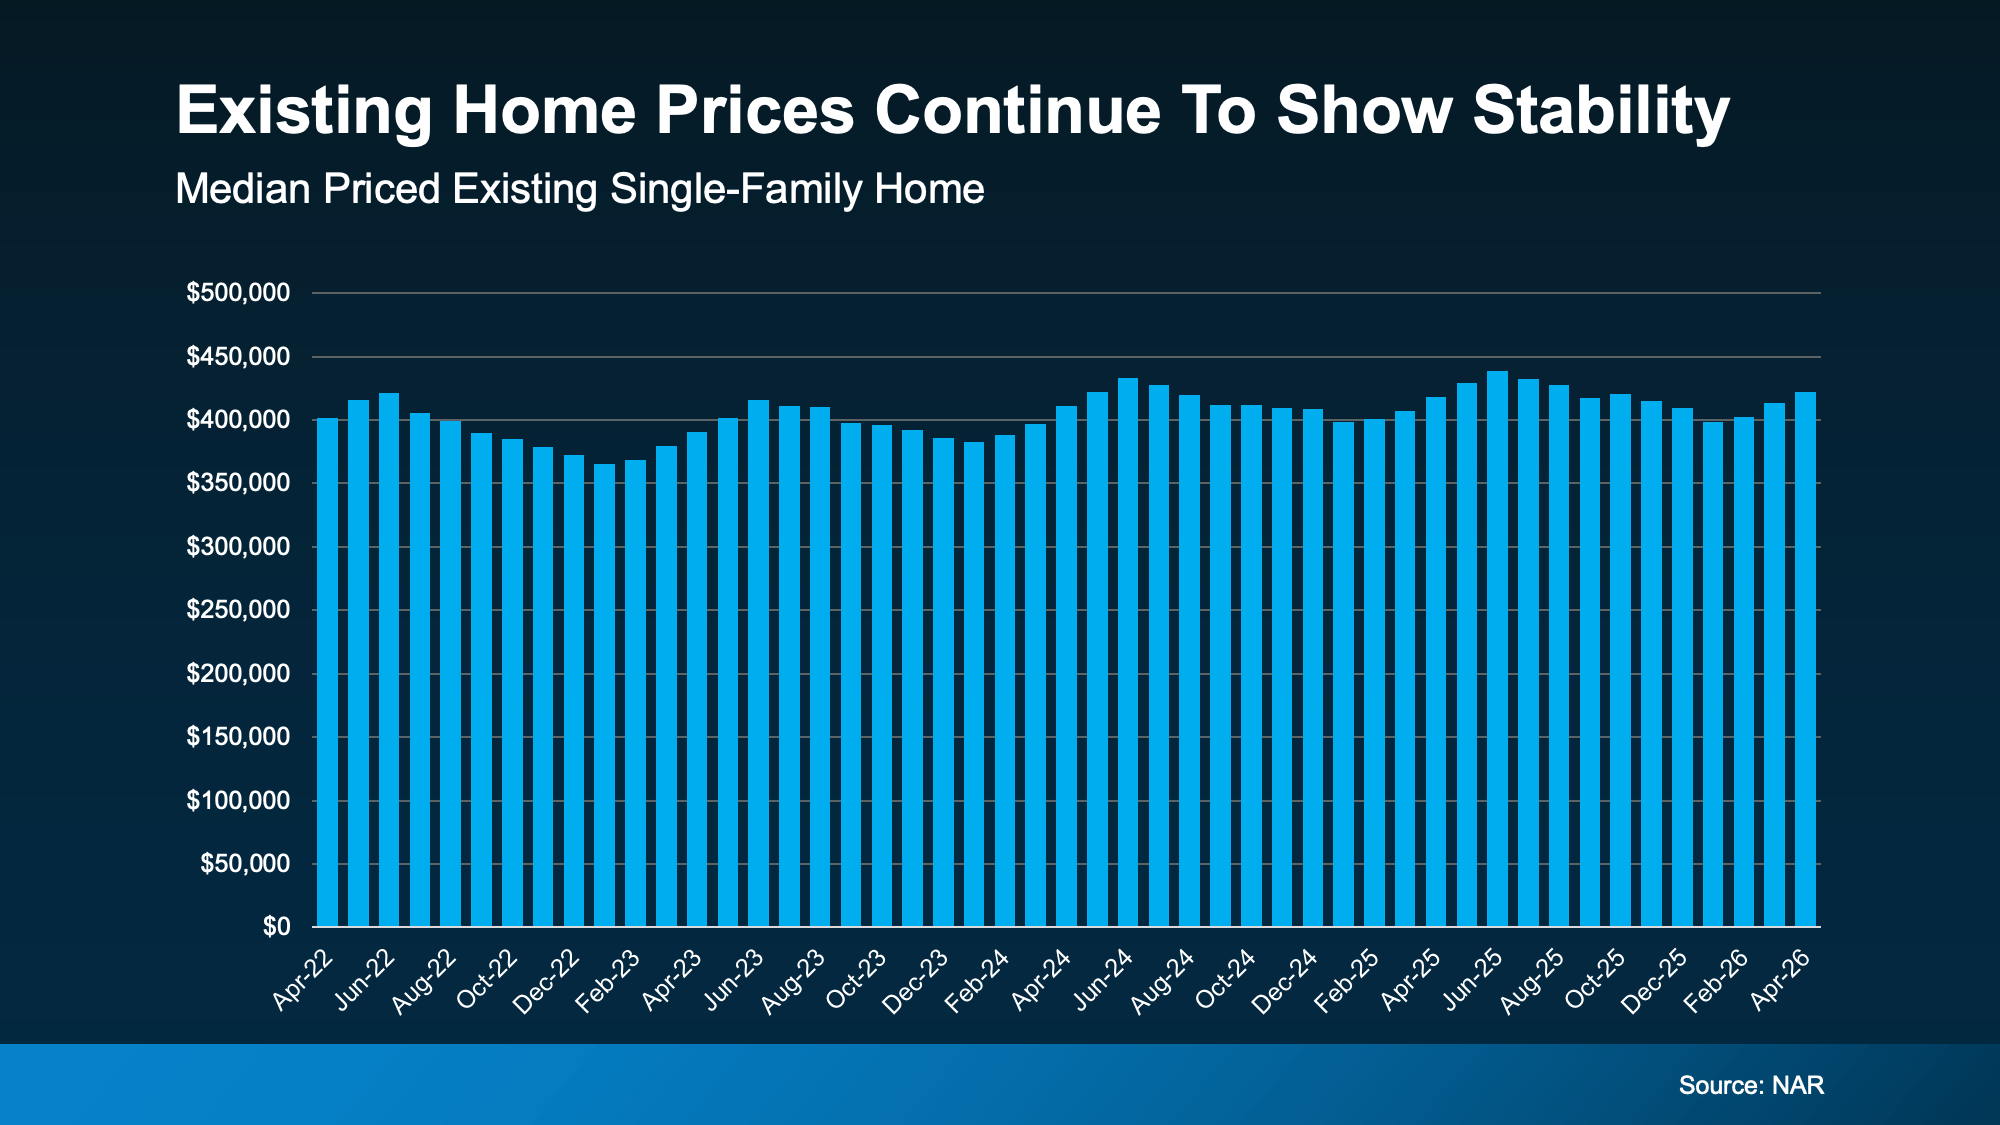
Part of what's keeping prices this stable is that buyers finally have more choices. That means less competition, more negotiating power, and more time to find the home that actually fits your life, not just the one you had to grab before someone else did.
And that gives you a chance to hopefully find something that works for your budget, even with today’s rates. At the same time, you're not losing ground pricewise while you take time to make a careful decision.
While mortgage rates remain a challenge, affordability is about much more than just interest rates. Wage growth, home prices, available inventory, negotiating opportunities, and financing options all play an important role in determining what’s possible for you.
At the Bob Henderson Team, we help buyers throughout the Kansas City Metro, including the Northland, Clay County, Platte County, Jackson County, Johnson County, and Wyandotte County, understand the complete picture—not just the headlines. By combining local market expertise with trusted lending partners, we can help you evaluate your options, understand your buying power, and create a strategy that fits your goals and budget.
If you're wondering whether buying a home in Kansas City still makes sense for you, let's connect and run the numbers together. You may have more opportunities available than you realize.
Trusted. Strategic. Local.Bob Henderson is a third-generation REALTOR® with deep Kansas City roots and 20+ years of corporate leadership experience. He brings a rare blend of business acumen and h....
Quick gut reaction. Which investment do Americans trust more than stocks, gold, savings accounts, and bonds? The answer hasn't changed in 14 years. It's real estate. And this year, that answer
Saving for a down payment can feel like the hardest part of buying a home. And with affordability as tight as it’s been lately, it’s fair to wonder how anyone manages it right now. Here
A few years ago, sellers could get away with saying "no" to just about everything.No repairs.No concessions.No negotiation.If buyers wanted the house, they pretty much had to take it on the seller's
If affordability has been the biggest thing standing between you and a home, there's a little good news. Asking prices have started to come down.The typical seller listed their house for a
 The information displayed on this page is confidential, proprietary, and copyrighted information of Heartland Multiple Listing Service, Inc. (
Heartland MLS
). Copyright 2026, Heartland Multiple Listing Service, Inc. Heartland MLS and Bob Henderson Team do not make any warranty or representation concerning the timeliness or accuracy of the information displayed herein. In consideration for the receipt of the information on this page, the recipient agrees to use the information solely for the private noncommercial purpose of identifying a property in which the recipient has a good faith interest in acquiring. Data last updated on September 23, 2026 1:31 AM UTC
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owners behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
